2023 Year in Review
Defense, Government & Intelligence | Security | Critical Infrastructure | Maritime
Download Full Report
Year in Review
Main Street Capital Acquires Cybermedia Technologies (CTEC)
- Main Street Capital (NYSE: MAIN) made its first acquisition in the government contracting sector with its acquisition of Cybermedia Technologies (“CTEC”), a professional services company that delivers solutions to the federal government, focused on human capital development and digital modernization.
- CTEC’s over 300 employees will continue their work with agencies, including the DHS, IRS, and OPM, while collaborating with Main Street to expand the company’s agency footprint and service offerings through organic and inorganic growth
Eqlipse Technologies Acquires CollabraSpace
- Eqlipse Technologies (“Eqlipse”), a portfolio company of Arlington Capital Partners, acquired CollabraSpace, a leading provider of real-time collaboration and enterprise software development solutions to both government and private industry.
- With the addition of CollabraSpace, Eqlipse now has over 600 employees and generates more than $200 million in revenue.
- The acquisition provides Eqlipse with additional capabilities and resources critical in the delivery of its mission-oriented solutions to Department of Defense and Intelligence Community customers.
ASRC Federal Acquires Broadleaf
- ASRC Federal acquired Broadleaf, Inc. (“Broadleaf”), a leading provider of information technology services including cybersecurity, network engineering, and cloud migration.
- The acquisition adds nearly 600 employees to ASRC Federal and expands their presence at key U.S. Army commands, specifically Aberdeen Proving Ground, and within the U.S. Navy and Defense Counterintelligence and Security agency.
- The acquisition further strengthens ASRC Federal’s presence within its current customers and provides an opportunity for growth to new customers.
Michael Baker International Acquires Tidal Basin
- Michael Baker International, a global provider of engineering, planning, and consulting services acquired Tidal Basin, a program manager for emergency response and disaster planning.
- Tidal Basin will continue to operate as a stand-alone Company and will work in connection with Michael Baker to serve their shared customer base.
- While not consolidated operationally, the two Companies are expected to create significant revenue synergies for DC Capital while working towards their shared mission of improving the nation’s recovery efforts and infrastructure resiliency.
Anduril Industries Acquires Blue Force Technologies
- Anduril Industries (“Anduril”) acquired Blue Force Technologies (“Blue Force”), a developer of autonomous aircraft with an integrated aerostructures division serving a wide range of defense and commercial customers.
- Blue Force has been developing Fury, a group 5 autonomous air vehicle with fighter-like performance since 2019.
- The acquisition expands Anduril’s existing autonomous fleet to now include large high-performance aircraft, and significantly increase the Company’s reach and impact within the Department of Defense.
Godspeed Capital Forms Intelligence Platform, Adds Seaford Consulting
- Godspeed Capital announced the formation of its new intelligence platform with a number of acquisitions, including Seaford Consulting, a provider of services to the Intelligence Community including IT, business transformation, and financial management.
- Seaford’s highly cleared employee base has spent over 13 years delivering successful solutions on full and open contracts to its customer, and will now join the larger Crimson Phoenix platform to continue delivering their services across customers within the Intelligence Community.
Defense, Government & Intelligence
Russia and Ukraine fighting intensified in 2023, with many calling the conflict a “war of attrition.” Since Russia’s initial invasion of Ukraine in February 2022, neither side has been able to make a significant breakthrough, and there remains little sign that a peace deal is on the horizon. The U.S. continued its support of Ukraine, with President Biden making an unannounced visit to Kyiv in February 2023 and providing additional security assistance packages throughout the year. As of December 2023, the U.S. Government has provided over $45 billion in military aid to Ukraine alone.
Government funding levels for defense and space-related technologies continued to rise in 2023. The government is diversifying its approach and allocating financial resources to the space market through new channels, including loans and other transaction agreements. The Biden Administration’s FY 2023 budget included historic science and technology investments, surpassing $200 million in total federal R&D for the first time in history. In the proposed FY 2024 budget, the U.S. Space Force funding exceeds that of NASA by $1 billion, confirming space and space-based intelligence as a priority and focus of the U.S. government.
On October 7th, the Israel-Hamas war began when Hamas launched an unprecedented attack on southern Israel. Shortly thereafter, President Biden visited Israel, clearly demonstrating who the United States sides with on this conflict. As the proposed $14.3 billion in aid to Israel remains in flux, U.S. Defense Secretary Lloyd Austin recently vowed to keep Israel armed with “critical munitions, tactical vehicles, and air defense systems.”
On October 31st, the Department of Veteran Affairs (VA) named a list of 30 companies that were given awards for the 10-year, $60.7 billion T4NG2 contract vehicle. The VA indicated that its plan is to continue legacy work and issue new task orders on the original T4NG contract until the ceiling is reached. According to GovTribe data, the current T4NG vehicle has issued approximately 65% of its ceiling value to date across 587 awards. Notable T4NG2 awardees include Deloitte, Mantech, and SAIC.
Large government contractors continue to stand up internal venture capital arms, with the goal of investing in startup companies across defense, artificial intelligence/machine learning, and cybersecurity areas. These contractors include Booz Allen Hamilton, SAIC, Lockheed Martin, RTX, and most recently, Maximus. As the government looks to speed up innovation and adoption of new technology, many believe venture capital and growth equity will continue to increase in popularity across the federal contracting space.
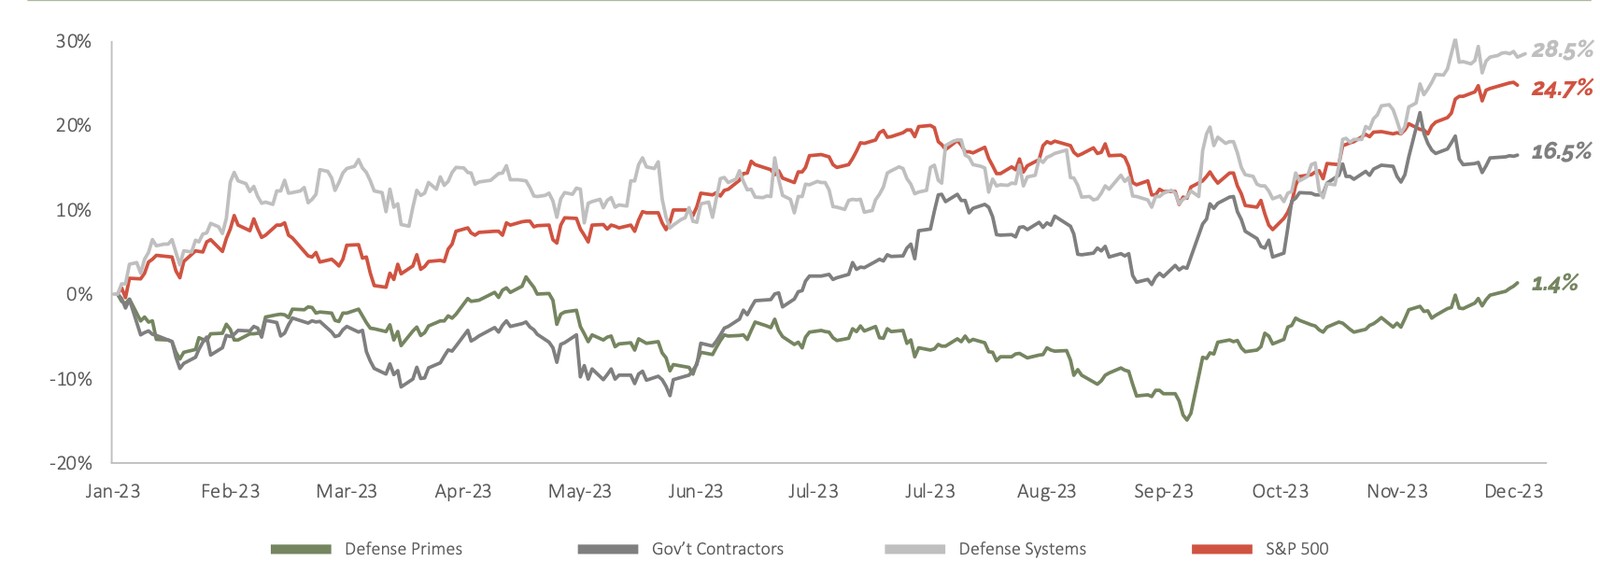
Despite the economic turbulence in early 2023, largely stemming from rapid inflation, interest rate hikes, and the banking crisis, equity markets performed quite well, with the S&P 500 finishing up 24.7% for the year.
Defense and government contractors continued to perform well in 2023 on the heels on geopolitical events, such as the ongoing Russia-Ukraine war, the Israel-Hamas events, and ongoing government initiatives, including IT system modernization, AI/ML adoption, and national security.
Looking ahead to 2024, economists and analysts are bullish on the outlook for the economy, predicting that the Federal Open Market Committee (“FOMC”) will begin rate cuts by May and the markets will reach new all-time highs during the calendar year.
The M&A activity in the DGI industry remained quite strong in 2023, with the majority of deals skewing to sub $100 million. Towards the end of the year, a handful of landmark transactions were announced in the industry, including Bain Capital’s purchase of Guidehouse and the combination of Amentum and Jacobs’ Critical Missions Solutions (“CMS”) business. With the volatile debt markets in 2023, many DGI-focused private equity groups turned to smaller add-on acquisitions as opposed to larger platform purchases.
Trailing Twelve Months (TTM) Public Equity Index
 Open page 7 of the report →
Transactions by Quarter
EBITDA Valuation Multiples
Multiples are average TEV / EBITDA for each public company group as of December 31, 2023, and are provided for reference purposes only. Public market multiples may differ materially from private company transaction pricing.
Select 2023 Transactions
(A) Announcement date. ND = not disclosed.
Physical & Cyber Security
Artificial intelligence and machine learning (AI/ML) have become increasingly important to cybersecurity as the technology matures. AI can help counter cyberattacks, and ML algorithms can analyze data in real-time more efficiently than humans. AI can learn to identify patterns that indicate a threat, making it easier to predict and prevent attacks. According to IBM, businesses that use AI to detect and respond to data breaches save an average of $3 million.
Hackers are also turning to AI/ML to find system vulnerabilities. Bad actors are employing AI algorithms that scan for and identify vulnerable systems, thus increasing the quantity and efficiency of threats. AI is also being used to create large numbers of targeted and personalized phishing emails designed to manipulate recipients.
The Cybersecurity and Infrastructure Security Agency published guidelines in November to ensure secure development practices in AI. The guidelines emphasize incorporating security in new AI applications and using a "secure by design" approach, as well as ensuring security in operational practices and maintenance.
President Biden signed an executive order focused on addressing the rapid advancements of AI. The order lays the groundwork for the U.S. government to embrace AI as a tool in national security while also urging companies to develop the technology safely.
The federal government released the long-awaited draft of the Cybersecurity Maturity Model Certification (CMMC) guidelines, which lays out DoD expectations for how government contractors are expected to maintain and protect sensitive military data. The CMMC draft contains no mention of waivers for small businesses, meaning smaller contractors may need to undertake the expensive and lengthy task of obtaining necessary certification levels. Prime contractors will be tasked with ensuring compliance among applicable suppliers, introducing costs associated with oversight and enforcement.
Corporate cybersecurity customers seek shorter-term contracts from vendors after a volatile year, according to a recent Wall Street Journal report. In many instances, customers are seeking to shield themselves from suppliers who are acquired or are struggling financially.
Increasing emphasis on “sovereign cloud” networks: Cloud system users are becoming increasingly focused on where their data is stored in cloud networks. Sovereign clouds ensure data is stored on servers located on sovereign soil, which helps prevent unauthorized foreign access.
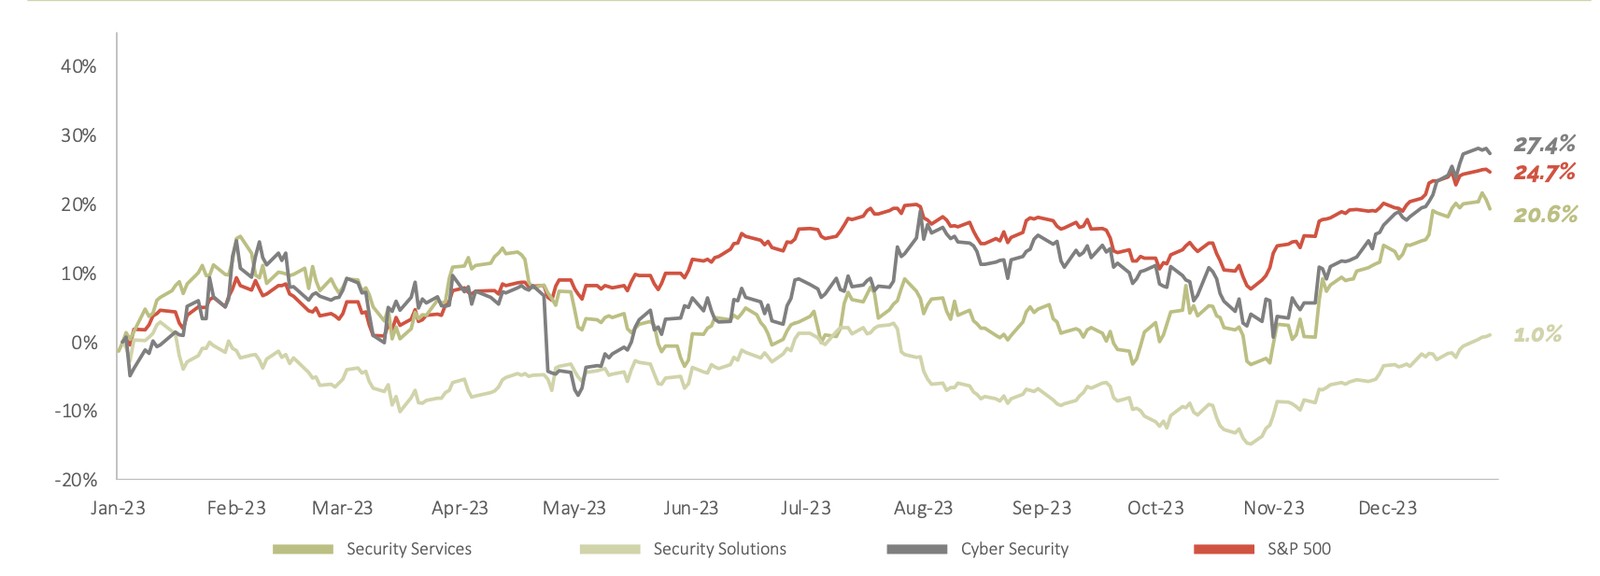
All indices finished positive in the last twelve months, driven by better-than-expected macroeconomic conditions and evolving security threats.
The Cyber Security index outperformed the S&P 500, reflecting investors’ awareness of the increasingly important service of cyber threat mitigation. In particular, the emergence of AI threats has caused companies to rethink how they will safeguard sensitive data.
The Security Solutions index, which has substantial exposure to the real estate sector, posted relatively weak gains. Customers in the commercial real estate space sought to cut back on spending in various areas, including security, to offset rising interest rates and vacancies.
2023 M&A activity remained relatively consistent compared to 2022, particularly in the security solutions industry. Many private equity firms and their portfolio companies, such as Altas Partners - Pye-Barker, expanded their security offerings and geographical footprints. Strategic buyers, such as Cisco, have focused their M&A activity on cybersecurity and security technology targets to develop a full suite of security offerings.
Trailing Twelve Months (TTM) Public Equity Index
 Open page 14 of the report →
Transactions by Quarter
EBITDA Valuation Multiples
Multiples are average TEV / EBITDA for each public company group as of December 31, 2023, and are provided for reference purposes only. Public market multiples may differ materially from private company transaction pricing.
Select 2023 Transactions
(A) Announcement date. ND = not disclosed.
Critical Infrastructure
The EPA completed its 2023 Drinking Water Infrastructure Needs Survey and Assessment, encompassing the capital needs of all 50 states and U.S. territories, including over 100,000 planned municipal investments. The assessment highlighted a total planned investment in U.S. drinking water infrastructure over the next 20 years of roughly $625 billion. Further analysis of the survey breaks down the number into subsectors where money will be directed, including: Water Networks – 58.6%; Pump Stations – 8.7%; Drinking Water Treatment – 17.1%; Other – 2.8%; Water Resources – 12.8%.
The influx of money to the municipal water industry and greater focus on resource recovery caused by heightened discharge regulations has led to a shift in the industry to capture the “value of waste” by recovering key nutrients and energy from water treatment byproducts. The growing emphasis on circular economies creates a new revenue stream for the municipal industry, which is increasingly reducing costs with onsite cogeneration while also offloading byproducts to industrial partners. Circularity not only benefits municipalities but also their equipment suppliers and operating partners who are increasingly being tapped to handle more complex challenges, including solids handling, dewatering, storage, and destruction/reuse.
Increasing regulation of wastewater discharge has led many companies to create inventive ways to service new industrial and municipal customers subject to rapidly evolving regulations. The rate of regulatory change and the capital investment required to meet discharge limits has led many customers to outsource ownership of filtration equipment, paying for throughput on an as-needed basis. Called “Filtration as a Service” (FaaS), outsourcing allows customers to focus on their core competency while receiving highly customized filtration services without having to invest in new equipment that may become obsolete in the face of new discharge limits. FaaS often includes the integration of monitoring systems and data tools to optimize system performance.
The EPA updated its Lead and Copper Revisions to give U.S. utilities just 10 years to replace 9 million lead service lines. The new guidelines require utilities to eliminate the number of lead service lines by 10% each year and distribute point-of-use filters if testing exceeds a certain threshold of lead. The EPA estimates that the approximately 9 million lead service lines will cost $5,000 to $5,500 per line to replace, for a total cost of $46 billion. This exceeds the $15 billion allocated for lead pipe replacement by the Infrastructure Investment and Jobs Act, even after including another $11.7 billion injected into state revolving funds.
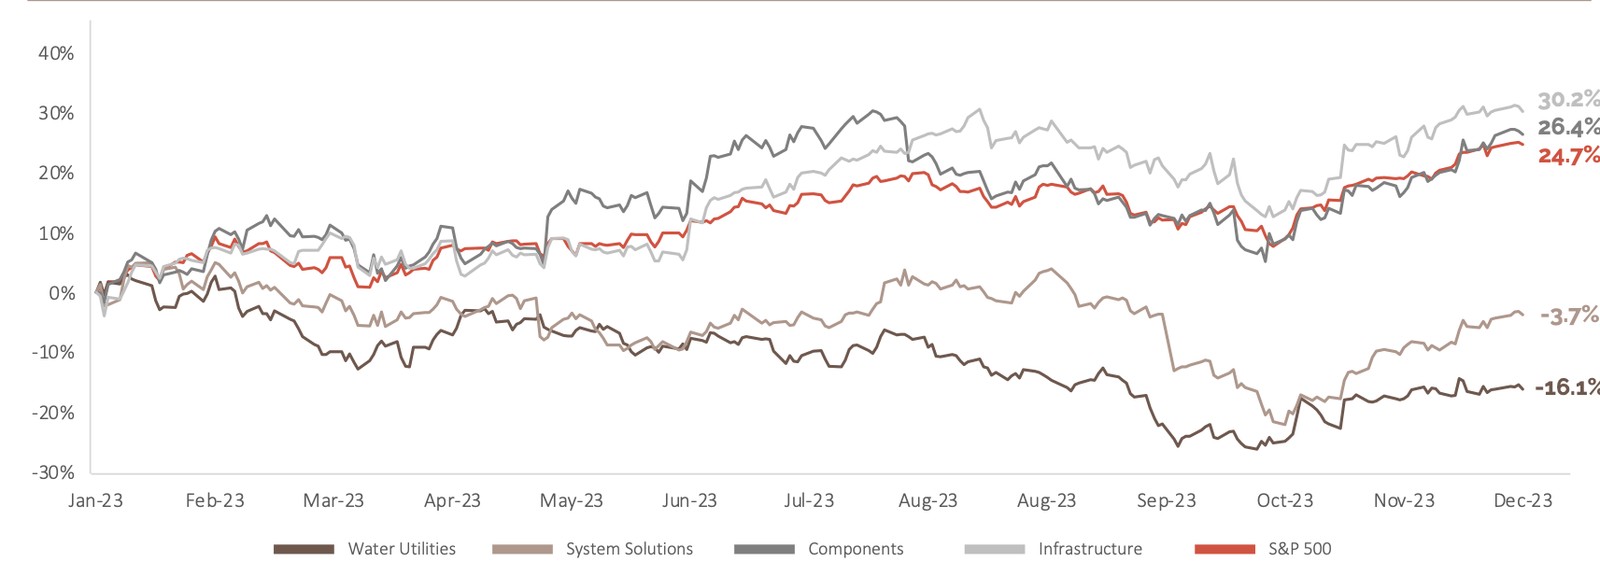
TMG’s indices closely tracked the S&P 500 throughout 2023, with Infrastructure and Components both outperforming the benchmark.
Infrastructure continues to benefit from historic government investment, while component providers were insulated from the worst of inflation due to their decreased reliance on capital expenditures and ability to pass cost increases on to customers faster, thanks to shorter project lifecycles.
Utilities and System Solutions lagged the S&P as margins were more negatively impacted than their peers due to their longer project lifecycles and inability to expeditiously pass through costs to the end customer as input costs rose.
2023 continued the previous year's declining trend in acquisition activity due to interest rate hikes, increasing the cost of capital for both strategic and financial sponsors. Acquisition activity from strategics witnessed a particular downturn, as persistent inflation throughout the year increased input costs, weighing on profitability and available cash for acquisitions.
Trailing Twelve Months (TTM) Public Equity Index
 Open page 22 of the report →
Transactions by Quarter
EBITDA Valuation Multiples
Multiples are average TEV / EBITDA for each public company group as of December 31, 2023, and are provided for reference purposes only. Public market multiples may differ materially from private company transaction pricing.
Select 2023 Transactions
(A) Announcement date. ND = not disclosed.
Maritime Transport & Facilities
While high shipping costs are frequently blamed for causing inflation, the shipping industry was also impacted negatively on a number of fronts by rising global inflation throughout 2023. Rising costs from direct inputs such as oil and steel decreased profitability, while rising costs for offshore projects including oil rigs and wind farms reduced revenue and backlog across the maritime industry as certain projects became economically unviable.
2023 experienced the largest ever yearly addition of new shipping capacity, with approximately 2.5 million twenty-foot equivalent units. Coupled with declining demand due to inflation and higher interest rates, container shipping rates fell about 35% through November of 2023 before increasing on account of instability in the Red Sea. A report by Sea-Intelligence highlighted the industry’s current level of overcapacity could take at least four years to be resolved. Capacity is currently being buoyed by an aging fleet (average age of over 14 years) and an order book set to deliver an additional 25% capacity.
Current woes in the shipping industry, including rising input costs and lower rates, have led many in the industry to undertake dramatic cost-saving initiatives, including reducing headcount and capital expenditures. Industry leader Maersk announced 10,000 job cuts in 2023, in addition to a 17% reduction in capex from 2023 to 2024.
The Russian/Ukraine War has continued its impact on the shipping industry into 2023. Following the EU’s sanctions on most energy imports from Russia, excluding Liquified Natural Gas (LNG), EU LNG imports from Russia rose 38% in 2022. In an effort to continue stemming money flowing to Russia’s war effort, the EU reached a deal in December of this year, allowing nations to ban Russian LNG imports. 2023 also witnessed the collapse of Russia and Ukraine’s Black Sea Grain Deal, an agreement brokered by Turkey to allow the exportation of food and fertilizer through select Ukrainian ports. The expiration of the agreements was immediately followed by Russian strikes on key port infrastructure on Ukraine’s Danube River, which caused wheat futures to jump 8.5% overnight.
Since the middle of November, Houthi rebel groups in Yemen have conducted repeated attacks on commercial vessels in the Red Sea and have stated that Israeli-linked ships will continue to be targeted as long as Israel continues its aggression on Gaza. Conflict in the Red Sea (responsible for about 15% of global trade) has led many shipping companies, including market leaders such as Maersk, CMA CGM, and Hapag-Lloyd, to divert to alternative routes. The longer, more expensive routes have led to an increase in container shipping rates since November (+20%) and an increase in the share price of many publicly traded shippers.
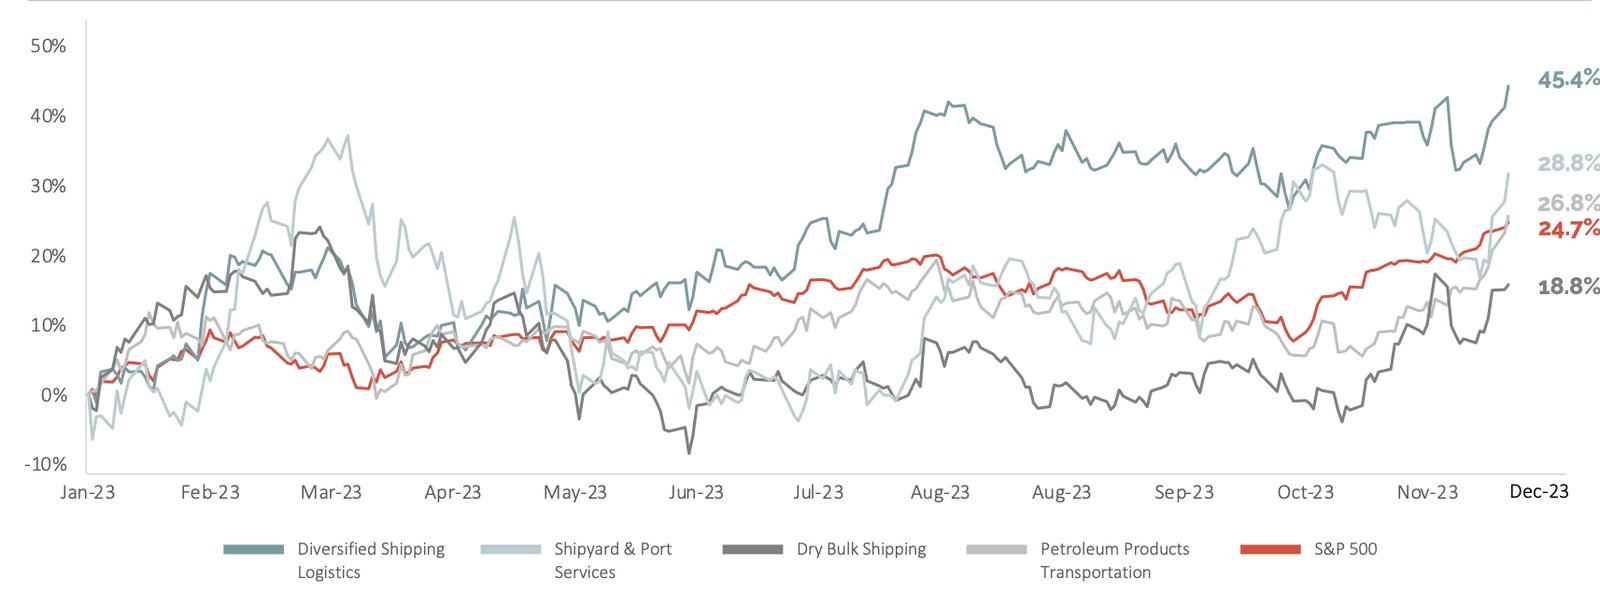
TMG’s maritime indices performed well throughout 2023 with both Shipyard & Port Services as well as Petroleum Products Transportation tracking the S&P throughout the year.
Dry Bulk shipping lagged the S&P for most of 2023 due to declining shipping rates but staged a rally in Q4 on account of increasing rates.
The Logistics Index outperformed the S&P, aided by Matson and ArcBest, which will benefit from higher rates and don’t have as much exposure to conflict in the Red Sea.
While 2023 witnessed another decline in deal activity due to elevated borrowing costs, certain trends become apparent upon review of deals individually. Most notably, shippers continue to deploy record high pandemic-era profits to diversify their operations into areas including ports and logistics; a strategy to protect themselves from a projected decline in container shipping rates.
Trailing Twelve Months (TTM) Public Equity Index
 Open page 30 of the report →
Transactions by Quarter
EBITDA Valuation Multiples
Multiples are average TEV / EBITDA for each public company group as of December 31, 2023, and are provided for reference purposes only. Public market multiples may differ materially from private company transaction pricing.
Select 2023 Transactions
(A) Announcement date. ND = not disclosed.
Read the 2023 Year in Review
- Jun 2024Monthly Middle Market M&A Insider Report (May 2024)
- Apr 2024Q1 2024 Mergers & Acquisitions Market Update
- Mar 2024Monthly Middle Market M&A Insider Report (February 2024)
- Aug 2023Monthly Middle Market M&A Insider Report (July 2023)
- Aug 2023Q3 2023 Mergers & Acquisitions Market Update
- Jul 2023Q2 2023 Mergers & Acquisitions Market Update
Browse every 2024 post in the archive →Planning a sale or acquisition? See our M&A advisory and valuation services.
Speak With the Team
Download the Full 2023 Year in Review
Complete deal tables, valuation multiples, public company comps, and contract awards across all four sectors.
The information provided in this newsletter is for informational purposes only and does not constitute an offer to sell or the solicitation of an offer to buy any of the securities mentioned herein. Past performance does not guarantee future results. None of the information or analyses presented are intended to form the basis for any investment decision, and no specific recommendations are intended. Any performance mentioned does not include transaction fees and costs, which would reduce an investor's return. An investment cannot be made directly in these custom market indices. Public market valuation multiples are provided for reference purposes only and reflect traded equity values, which may differ materially from private company transaction pricing.
The logos and company names used in this report are for illustration purposes only, and the report is not associated with or supported by the owners of the trademarks.
© 2026 The McLean Group. All rights reserved. Securities transactions are conducted through McLean Securities, LLC, a member of FINRA/SIPC.